

The Build-to-Rent Liquidity Fix: How OIO Exemptions Unlock Institutional Foreign Capital
The Structural Capital Deficit in New Zealand Housing
For decades, New Zealand’s multi-unit residential sector has operated under an acute capital constraint. While domestic bank debt and private equity can fund early-stage site acquisition and horizontal construction, local institutional capital has rarely possessed the balance-sheet depth required to warehouse completed, cash-flowing residential portfolios over 30-year horizons. For developers entering the build-to-rent (BTR) sector, this dynamic created a prohibitive exit penalty.
Under the historic settings of the Overseas Investment Act 2005, overseas buyers were barred from purchasing existing residential property without satisfying the stringent benefit to New Zealand test administered by the Overseas Investment Office (OIO), a regulatory division of Toitū Te Whenua LINZ. While initial construction could proceed under the increased housing pathway, any subsequent divestment of an operational BTR complex to an overseas institutional fund ran into statutory roadblocks. Because domestic institutional investors such as KiwiSaver providers and local pension schemes allocate only a minor fraction of their balance sheets to unlisted residential assets, developers faced illiquid holdings and trapped equity.
The Statutory Solution: The Large Rental Development Pathway
The legislative introduction of the large rental development test fundamentally alters this underwriting equation. By establishing an objective statutory pathway under the Overseas Investment Act, the Crown created clear criteria for both initial development and the subsequent acquisition of operational assets by foreign entities.
Administered by Toitū Te Whenua LINZ, the pathway applies to developments meeting precise structural conditions:
- A minimum threshold of 20 or more residential dwellings configured on a single site or adjacent sites connected by common infrastructure.
- The operational assets must be offered under standard residential tenancy agreements subject to the Residential Tenancies Act 1986.
- The assets must be held under unified ownership and professional management rather than individual unit-titled divestment.
- The non-occupation outcome must be met, ensuring offshore purchasers and their associates cannot reside in the properties.
This statutory clarity eliminates the discretionary risk that previously characterized OIO screening. Global pension managers, sovereign wealth funds, and specialist multifamily REITs no longer need to construct convoluted economic arguments demonstrating unique net economic benefits simply to purchase completed rental assets. As long as the 20-unit floor and operational criteria are maintained, secondary market transactions can proceed with regulatory certainty.
De-Risking the Development Lifecycle and Solving Exit Risk
In property development finance, liquidity at completion dictates the cost of debt during construction. Lenders assess risk based on transparent refinance or takeout options. When the secondary purchaser pool is restricted to a small circle of domestic buyers, mezzanine and senior debt pricing reflect that illiquidity.
By allowing overseas institutional buyers to acquire existing 20+ unit developments, the reform creates an active secondary market. Domestic developers can execute their business models: acquire land, absorb planning and construction risk, stabilise the asset through tenant lease-up, and recapitalise by selling the income stream to global long-term institutional buyers. The capital released from these exits can then be redeployed into subsequent development cycles.
This mechanism aligns New Zealand with mature offshore markets such as the United Kingdom, the United States, and Australia, where BTR accounts for a significant proportion of total residential development. In those jurisdictions, separation between merchant builders and long-term asset holders drives efficiency, allowing specialist construction firms to build while patient capital handles ongoing operational management.
Mount Wellington and the Scale Model: Simplicity Living
The practical necessity of this liquidity framework becomes obvious when examining scale developments across Auckland. Simplicity Living, backed by the Simplicity KiwiSaver Scheme and led by managing director Shane Brealey, has pioneered high-efficiency, multi-unit BTR delivery across the region.
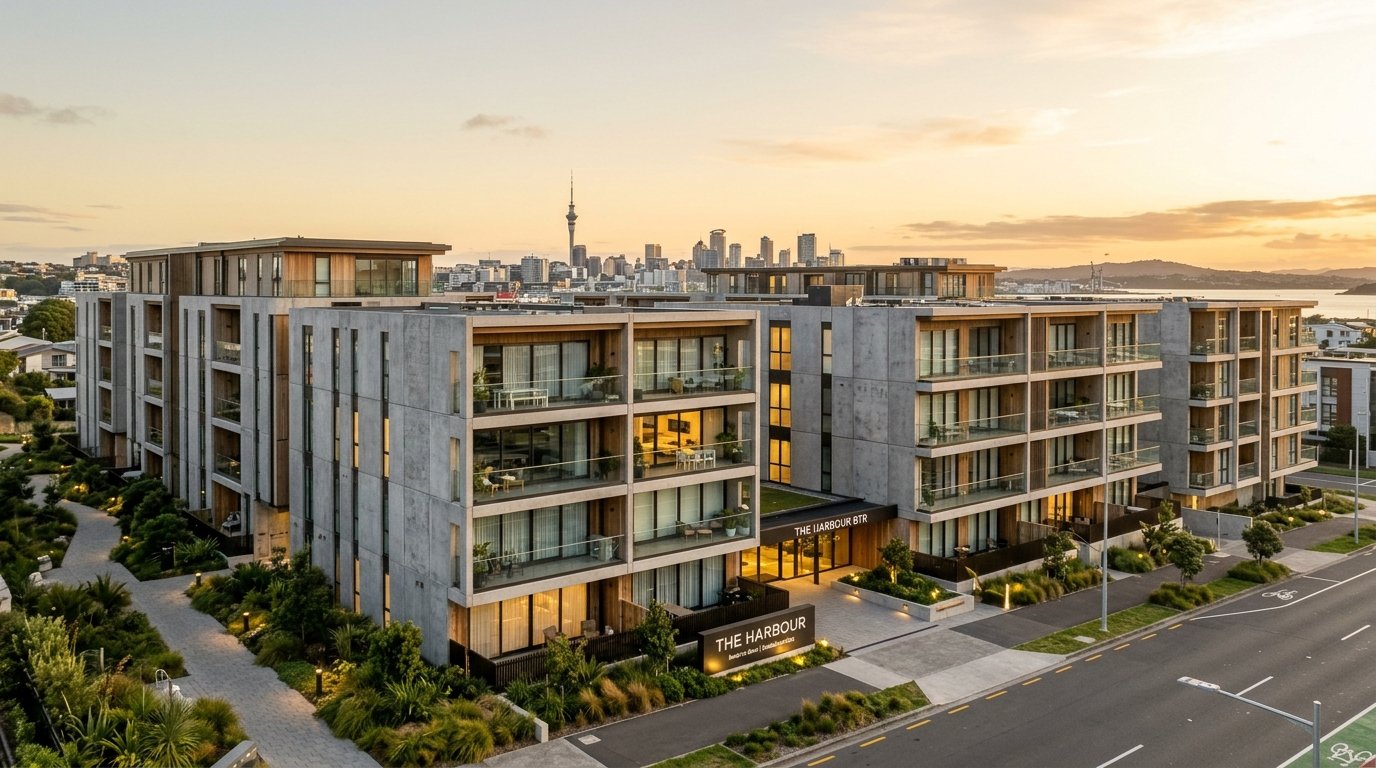
The provider’s Reiputa development in Mount Wellington serves as a tangible case study of the operational scale required to make build-to-rent viable. Comprising 297 high-quality apartments across multiple residential buildings, Reiputa was built using durable precast concrete and systematic offsite manufacturing techniques, achieving completion speeds well ahead of traditional residential construction norms. Situated close to Panmure transit links, the complex provides secure, long-term rental accommodation insulated from the erratic tenancy cycles typical of private, fragmented rentals.
Projects containing hundreds of units demand substantial capital commitments. A 297-unit development represents tens of millions of dollars in locked capital. While Simplicity Living operates an integrated build-to-hold strategy backed by KiwiSaver fund inflows, few domestic developers have access to recurring retail superannuation cash flows. For independent private developers to undertake assets of scale in suburbs like Mount Wellington, they require secondary market liquidity. Without the ability to trade stabilized 100-to-300-unit portfolios to global capital, local developers cannot scale their pipelines.
Property Council Data and the 25,000-Unit Horizon
The scale of latent supply waiting on this liquidity bridge is substantial. According to data tracked by Property Council New Zealand in conjunction with major commercial property agencies, the national BTR pipeline has shown steady upward momentum, with over 1,400 units completed, roughly 800 under active construction, and more than 3,300 units planned across key urban centres.
Research conducted by Property Council New Zealand indicates that with appropriate legislative certainty, including uninhibited OIO access and depreciation parity, institutional developers have the capacity to deliver 25,000 build-to-rent homes across New Zealand over the next decade. Industry leadership from Property Council New Zealand has consistently pointed out that the domestic banking sector cannot shoulder this development volume alone. Global pension funds manage tens of trillions of dollars searching for defensive, consumer-price-index-linked cash flows. New Zealand residential property provides an appealing yield profile, but only when offshore managers have an unencumbered path to both enter and liquidate positions.
Long-Term Structural Shift for the Rental Market
The OIO exemption for developments of 20 or more units marks a structural maturation in how New Zealand houses its urban population. By removing friction from the Overseas Investment Office consent process through Toitū Te Whenua LINZ, the Crown has established the legal architecture required to attract patient institutional capital.
For tenants, the shift from private individual landlords to well-capitalised institutional owners provides greater tenancy tenure, professional building management, and modern energy-efficient amenities. For developers, the reform removes the threat of balance sheet lockup upon practical completion. As international capital flows into New Zealand’s BTR sector, the statutory 20-unit exemption functions as the critical mechanism transforming build-to-rent from an experimental niche into an enduring pillar of national housing supply.